Buyer activity rose 1.8× during last year’s festive window and was back at its pre-season level within a month. The one band where a sale actually reduced activity was Entry: those buyers do not buy cheaper in a sale; they stretch into a discounted mid-range phone. Six takeaways from the Techarc InfiSights Festive Gain Score […]
Buyer activity rose 1.8× during last year’s festive window and was back at its pre-season level within a month. The one band where a sale actually reduced activity was Entry: those buyers do not buy cheaper in a sale; they stretch into a discounted mid-range phone. Six takeaways from the Techarc InfiSights Festive Gain Score report.
Measured against the June–August run-rate, buyer activity rose 1.8× in October–November 2025 — then returned to the pre-season baseline within a month, at 0.97×. The season rearranges when people buy far more than it changes how many of them do.
Entry was the only band where activity fell during the festive window, to 0.72× its pre-season rate, while Premium rose 2.13× and Mid 2.00×. Sub-₹12,000 buyers use a discount to stretch into a mid-range phone rather than to save money on a cheaper one.
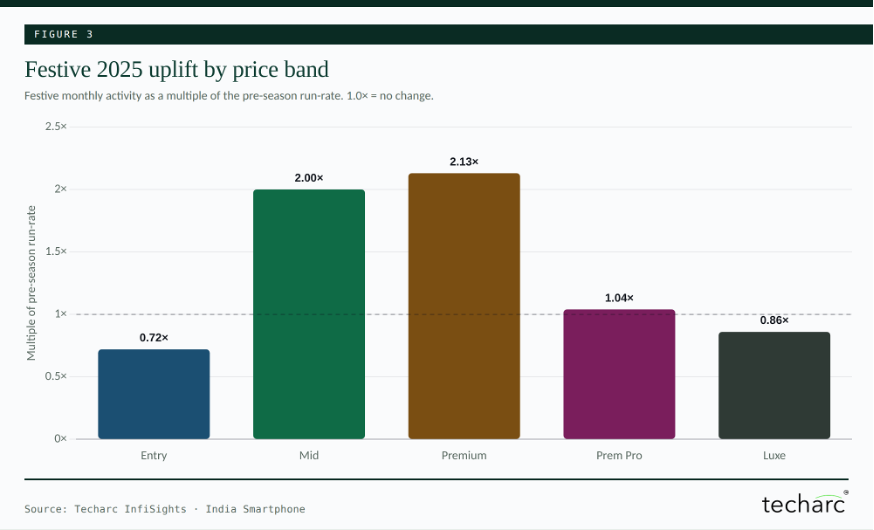
Entry is the only band where a festive sale reduces activity, as its buyers trade up rather than in.
Mid and Premium together account for 93% of expected festive demand. Everything above ₹50,000 and below ₹12,000 shares the remaining 7% — so most of the market’s noise sits where almost none of its volume does.
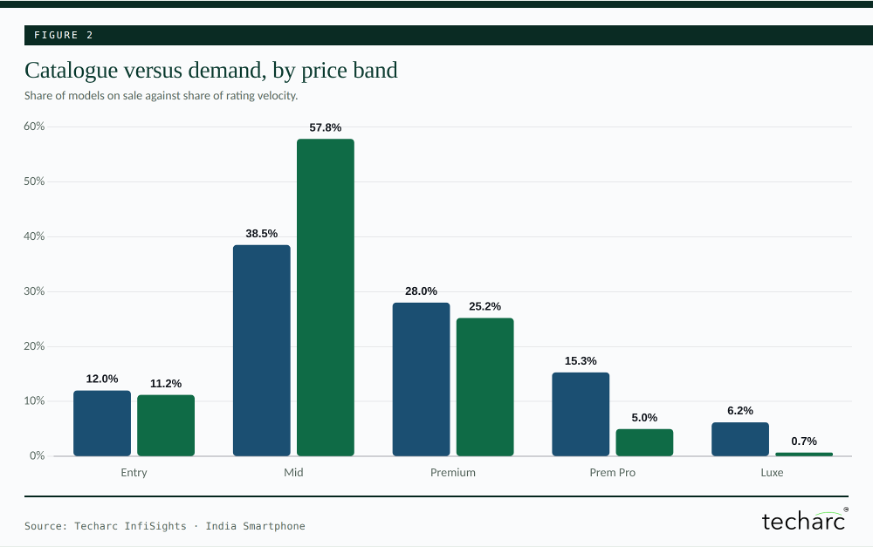
Catalogue share and demand share diverge most at the two ends of the price range.
Of phones launched in 2026, 69% now sell above their own launch price and only 7% have cut. Against last festive season, Mid is 24% dearer and Entry 18% — while Luxe is 3.5% cheaper. The bands that drive the sale are the ones that got expensive, which is where this year’s discounting gets difficult.
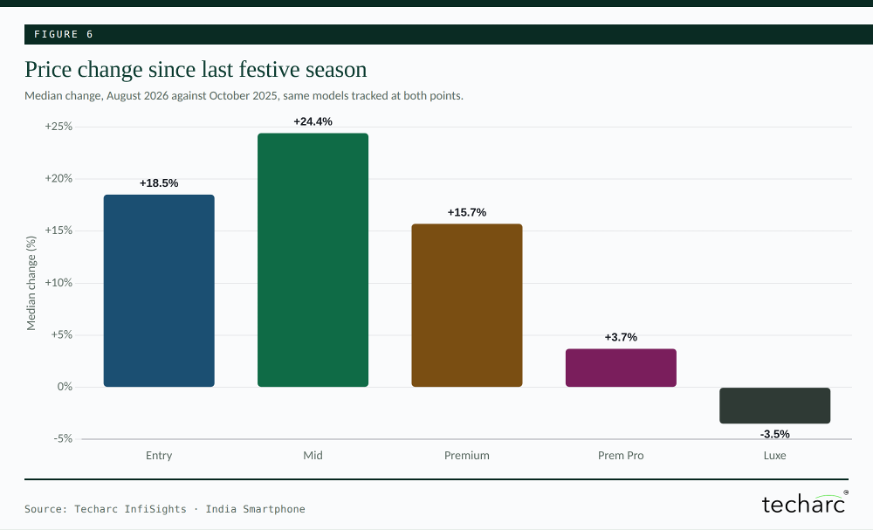
The bands that produce the festive lift are the bands where list prices rose most.
5G now adds about 1% to a phone’s price and faster charging nothing measurable. These features have not lost usefulness — they have lost scarcity, with 120Hz and IP64 now on more than nine in ten launches.
Five additional points of one-star share is associated with roughly 54% lower selling rate. Below 6% one-star, a model reaches the top decile 15.9% of the time; above 9%, just 2.7%.
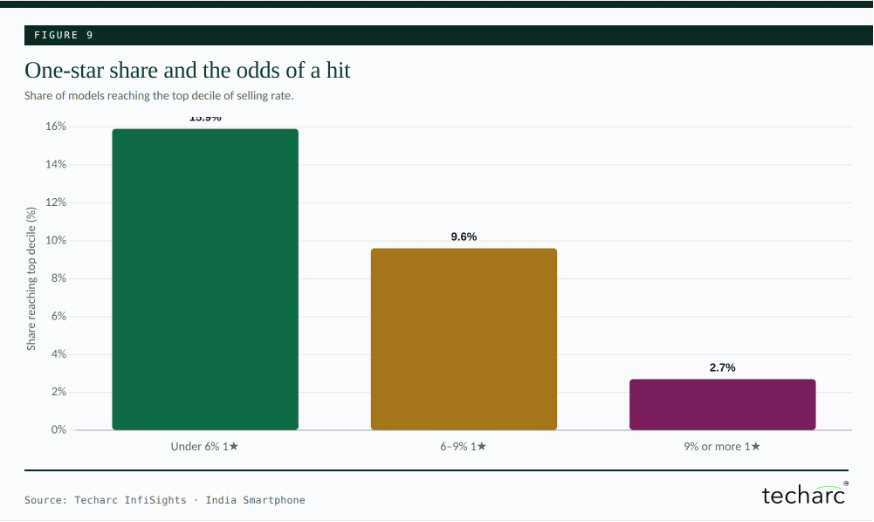
Cross-validated R² rises from 0.11 on price band alone to 0.43 once dissatisfaction and brand are added.
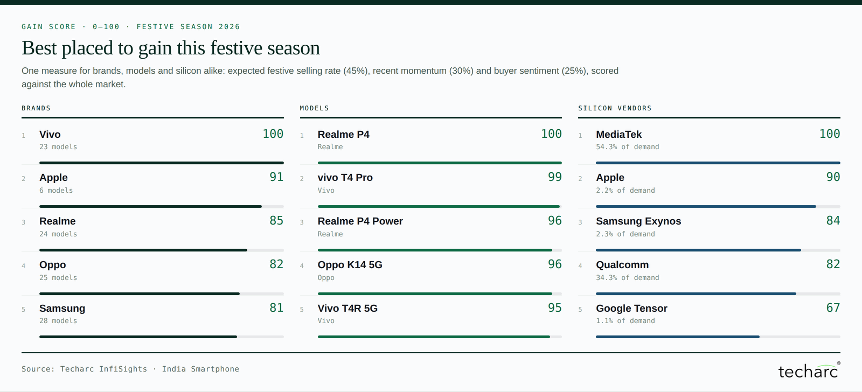
Gain score, 0–100, market-wide. Full segment-by-segment rankings for brands,
The weekly read on where technology is heading — 75,000+ subscribers across the industry.
Questions about our reports, dashboards, InsightsPro or a custom engagement? Send a note and the team will get back to you.