TVS Motor Q2 FY27: Record quarter, with electric doing the heavy lifting
TVS Motor Company posted its highest-ever quarterly revenue of ₹17,103 cr in Q2 FY27, up 44%, with profit up 52%. It held EBITDA margin at 13.0% despite what management called unprecedented material-cost inflation. Electric two-wheeler volumes more than doubled.
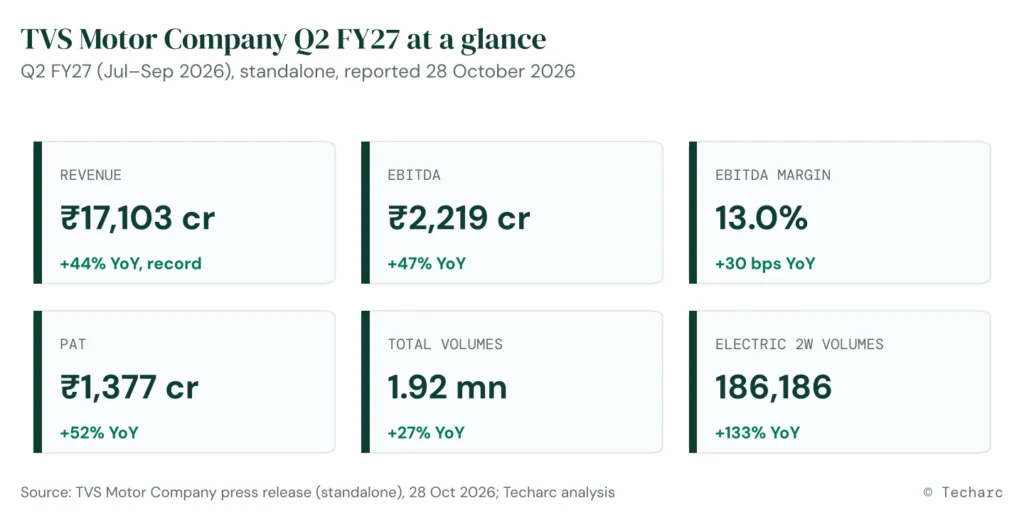
Figure 1: TVS Motor Company Q2 FY27 headline metrics (standalone). Consolidated revenue was ₹19,474 cr (+39%).
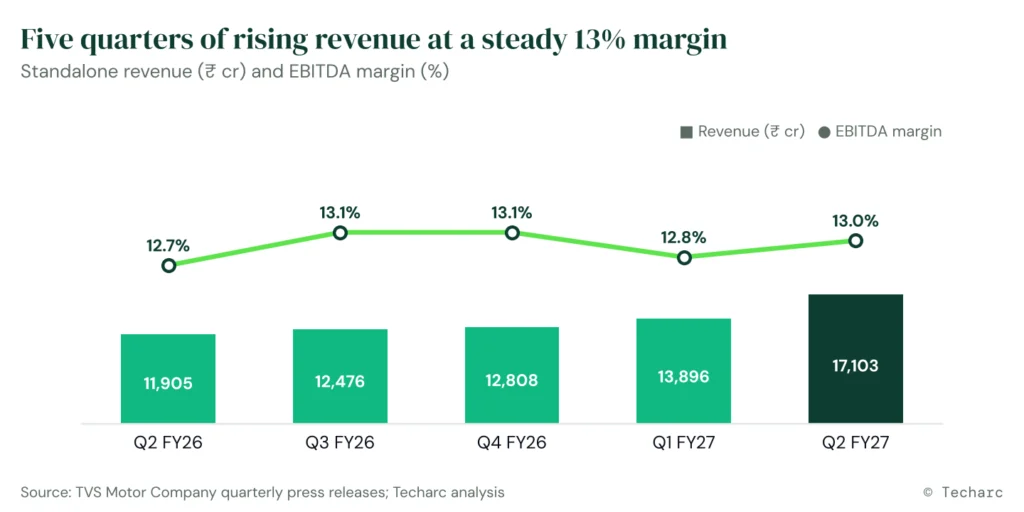
Figure 2: Five-quarter standalone revenue and EBITDA margin.
What the numbers say
Volumes rose 27% to 1.92 mn units, and revenue rose faster, at 44%. The gap comes from mix: more scooters, more electric two-wheelers, more three-wheelers and more exports, all of which carry higher revenue per unit than an entry motorcycle.
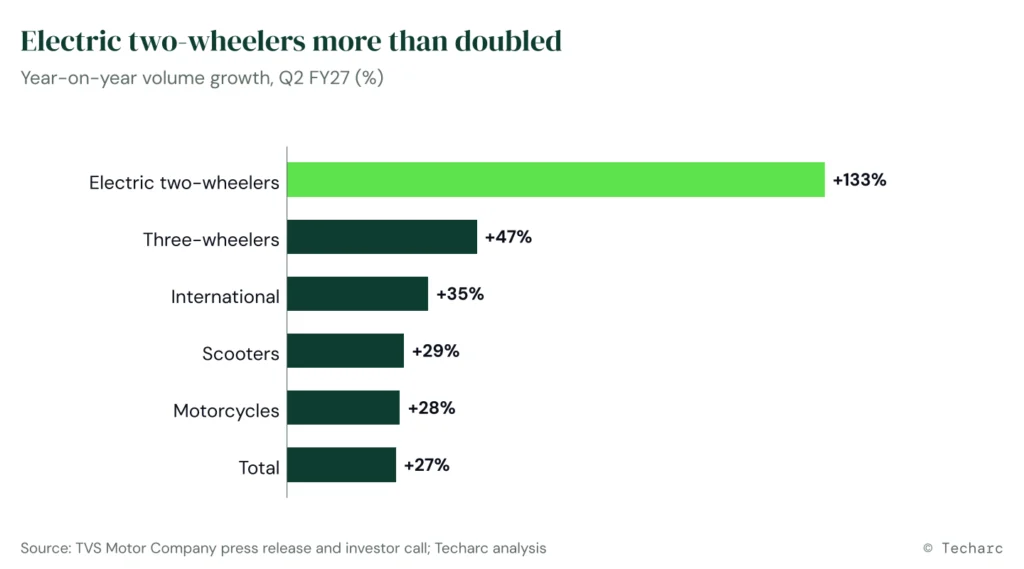
Figure 3: Volume growth by category.
Part of the growth comes from a soft base. Jul–Sep 2025 was weak because buyers waited for the GST cut on two-wheelers in late September 2025. But TVS also outgrew the market: management said its domestic ICE volumes rose 16% against industry growth of 10%, and its domestic electric volumes rose 129% against 84% for the industry.
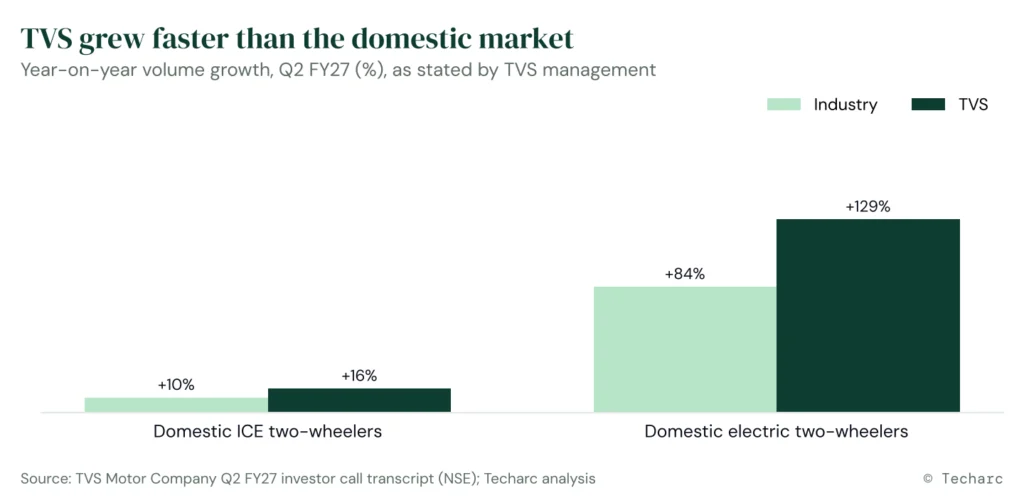
Figure 4: TVS against the domestic two-wheeler industry.
The margin held because pricing did. TVS described material-cost inflation as unprecedented and took price increases early in Q3. Holding 13% margin through a cost shock, while growing 44%, is the most impressive number in the quarter.
Electric two-wheelers and exports
Electric is now a core business, not a side bet. TVS sold 186,186 electric two-wheelers (iQube and Orbiter), up 133%. Management put electric two-wheeler penetration at 11.6% in September. iQube has passed 1 mn cumulative units, and production is moving from 60,000–65,000 a month toward about 80,000. Government incentives add about 1.3–1.4% of turnover.
Exports are the second engine. International volumes rose 35% to 539,000 units, and export revenue was about ₹4,378 cr, led by Africa, with Latin America and Asia also contributing. Three-wheelers grew 47%.
Norton is the brand-building play. The Manx R and Atlas are launching in the UK, Italy and France, with an India launch planned in the coming months. The board also approved demerging the consumer-finance business.
Techarc view
TVS’s quarter stands out on the measures that matter: growth, share gains, electric scale and margin. The upmarket shift is visible in the mix: scooters, electric models and exports are carrying the growth, not entry-level motorcycles.
The second half will be harder. Management expects single-digit ICE industry growth in H2 as the GST base effect fades, and cost inflation has not eased. TVS’s edge is that electric now gives it a growth engine independent of the ICE cycle. The test is whether electric can reach ICE-level margins as volumes approach 80,000 a month.
What to watch
- Electric two-wheeler share of TVS volumes after the festive season
- EBITDA margin in Q3 after the price increases, against continued cost inflation
- Norton’s India launch and pricing
- Export momentum in Africa and Latin America
- Progress on the consumer-finance demerger
Sources
- TVS Motor Company press release: highest-ever revenue with 44% growth in Q2: https://www.tvsmotor.com/media/press-release/tvs-motor-achieves-highest-ever-revenue-with-44-growth-in-q2
- TVS Motor Company Q2 FY27 investor call transcript (NSE): https://nsearchives.nseindia.com/corporate/TVSMOTOR_04112026174008_NSEBSEInvestorcalltranscript.pdf
- Autocar Pro: TVS Motor Q2 net profit rises 52%: https://www.autocarpro.in/news/tvs-motor-q2-net-profit-rises-52-percent-to-rs-1377-crore-revenue-jumps-44-percent-135533
- TVS Motor Company Q1 FY27 press release: https://www.tvsmotor.com/media/press-release/tvs-motor-records-38-precent-growth-in-revenue-and-highest-ever-profit-in-q1-2026-27